
If you run a bank, fintech, crypto exchange, or any regulated online business, the question is no longer whether to automate Know Your Customer (KYC) checks. The question is which AI-powered KYC verification solution can onboard real customers quickly while stopping deepfakes, forged documents, and synthetic identities. Fraudsters now use generative AI too, so a tool that looked strong two years ago may be a weak point today.
This guide explains how AI-powered KYC works, what to look for, which providers are worth shortlisting in 2026, and the latest news shaping the market. It is built for buyers who are comparing options and need a practical way to decide.
What is AI-powered KYC verification?
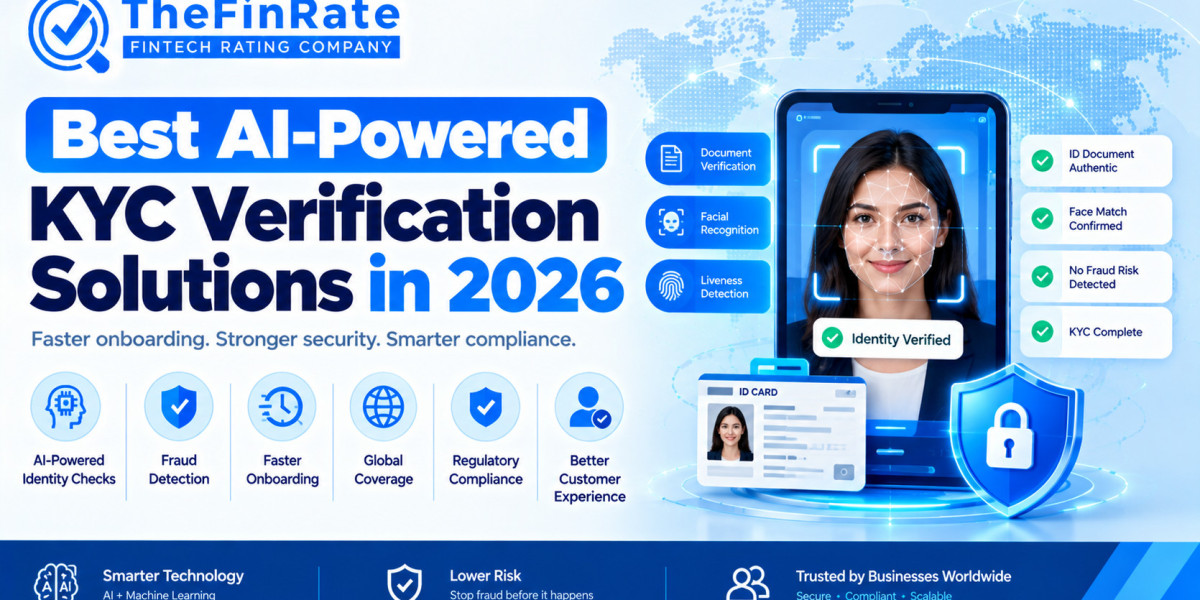
KYC verification confirms that a customer is who they claim to be and assesses their risk before you open an account or process payments. AI-powered KYC automates the steps that used to rely on manual review. A typical flow looks like this:
- Document capture and authentication. The customer photographs a passport, driver's license, or national ID. Machine-learning models read the data (OCR) and check security features, fonts, and signs of tampering.
- Biometric face match. The system compares a selfie with the portrait on the document.
- Liveness detection. The system confirms a real person is present, not a printed photo, replayed video, mask, or AI-generated face.
- Database and watchlist checks. The identity is screened against sanctions lists, politically exposed person (PEP) lists, and adverse media, which overlaps with AML screening.
- Risk scoring and decisioning. The platform approves, rejects, or routes the case to manual review based on your rules.
- Ongoing monitoring. Many providers now re-check customers over time instead of verifying them once and forgetting them.
Done well, this cuts onboarding from days to minutes, lowers manual review costs, and gives auditors a clear record of every decision.
Related reading
KYC works best alongside strong fraud and AML controls. For more on building out your compliance stack, see our guides to payment fraud detection software and AI-powered AML compliance software, and browse more fintech and payments resources at TheFinRate.
Why AI-powered KYC matters more in 2026
Three pressures are driving buyers toward newer tools:
- AI-driven fraud. Deepfakes, face swaps, and synthetic identities are cheaper and easier to produce. Face matching alone is no longer enough, and liveness detection has become a core control rather than an add-on.
- Regulation. Rules on remote identity verification, digital identity wallets, and data protection keep tightening in many markets.
- Customer expectations. People abandon sign-up flows that are slow or confusing, so you need strong security without added friction.
The news section below shows how quickly this is moving.
Latest KYC and identity verification news (October 2026)
Japan moves from photo-based KYC to chip verification
In Japan, the payment app PayPay announced that it will stop accepting photo-based identity verification with My Number Cards, driver's licenses, and driving history certificates by early November 2026. Users will instead verify through methods that read the RFID chip inside those documents. According to the company, the change responds to concerns about identity document images being misused after cyberattacks and data leaks. It also comes ahead of Japanese rules scheduled for April 2027 that will restrict how document images can be used in certain remote verification procedures. Reporting by The Japan Times indicates major Japanese banks are heading the same way, with Mizuho Bank already having dropped photo-based verification for online account opening.
What it means for buyers: NFC and chip reading is becoming a feature to ask about. If you serve markets with chip-enabled IDs, check whether a provider can read and validate the electronic data on the document, not only analyze a photo of it.
Innov8tif adds Malaysia's MyDigital ID to its eKYC platform
Malaysian provider Innov8tif Solutions announced on October 23 that it integrated the national MyDigital ID platform into its EMAS eKYC system. The integration adds a government-backed identity check on top of the document authentication and facial biometric verification that enterprises already use for remote onboarding.
What it means for buyers: Look for providers that connect to official government identity sources in your target countries. Checking a customer against authoritative records is stronger than relying only on a document and a selfie.
UK opens the GOV.UK Wallet sandbox to verification providers
On October 19, the UK's Government Digital Service opened applications for registered digital verification service providers to join the GOV.UK Wallet sandbox. The sandbox lets private-sector verification services test how they work with government-issued digital credentials, including the planned digital driving licence.
What it means for buyers: Digital identity wallets are arriving in the UK and across Europe, where EU member states are expected to make wallets available by the end of 2026. Ask providers how they will verify wallet-based credentials alongside traditional documents.
How we evaluated the best KYC verification solutions
When comparing providers, focus on criteria that affect fraud losses, conversion, and compliance, not just feature lists:
- Fraud detection accuracy: document forensics, deepfake and injection-attack detection, and strong liveness checks.
- Conversion and speed: pass rates for genuine users, time to decision, and mobile experience.
- Global coverage: supported document types, languages, and countries, plus local database integrations.
- Compliance coverage: KYC, KYB (business verification), AML screening, and ongoing monitoring.
- Data privacy and security: data minimization, retention controls, regional data hosting, and certifications such as SOC 2 and ISO 27001.
- Integration: quality of APIs and SDKs, no-code workflow tools, and time to launch.
- Pricing transparency: per-verification fees, minimums, and charges for extras such as re-verification.
- Support and auditability: case management, decision logs, and responsive support.
Best AI-powered KYC verification solutions in 2026
The providers below are widely used and commonly shortlisted. Capabilities, pricing, and ownership change often, so confirm current details with each vendor before you decide.
1. Persona: best for flexible, configurable workflows
Persona offers a modular identity platform where you assemble verification flows from building blocks such as document checks, selfies, database lookups, and case review. It suits companies that want to tailor onboarding by risk level and add steps without rebuilding their integration. It supports reusable verified identities, which can reduce repeat checks for returning customers.
Consider it if: you want control over workflows and expect your requirements to evolve.
2. Sumsub: best for all-in-one compliance, including crypto and fintech
Sumsub combines KYC, KYB, AML screening, and transaction monitoring in one platform and is popular with crypto and fintech companies operating across many jurisdictions. Its pitch is a single vendor for onboarding and ongoing compliance.
Consider it if: you operate in several regions and want verification and AML tooling together.
3. Jumio: best for large enterprises and banks
Jumio is a long-established provider focused on identity verification, biometrics, and AML screening for large, regulated organizations. It tends to appeal to institutions that need broad global coverage and mature enterprise support.
Consider it if: you are a bank or large enterprise with strict governance requirements.
4. Veriff: best for fast onboarding and global document coverage
Veriff emphasizes automated, real-time decisions across a large number of document types and countries, with a focus on fraud prevention and user experience. It is commonly used by online marketplaces, mobility, and fintech businesses that need quick approvals at scale.
Consider it if: onboarding speed and global reach are your top priorities.
5. Onfido (now part of Entrust): best for document and biometric verification inside a broader identity portfolio
Onfido built its reputation on document and facial biometric verification, and it now sits within Entrust's identity offering. That can suit organizations that want verification alongside wider identity and security products from one vendor. Confirm how the combined product line and roadmap fit your needs.
Consider it if: you want document and biometric checks from a provider with a larger identity and security portfolio behind it.
6. Socure: best for U.S. identity decisioning and fraud prevention
Socure uses large data networks and machine-learning models to verify identities and score fraud risk, with a strong presence among U.S. banks and fintechs. It is often chosen for risk-based decisioning that approves low-risk applicants instantly.
Consider it if: you are U.S.-focused and want data-driven approvals with fewer manual reviews.
7. Alloy: best for orchestrating multiple data sources
Alloy is an identity decisioning platform that lets financial institutions combine KYC, fraud, and AML signals from multiple providers into one workflow. It is less a single verification engine than a layer that orchestrates several.
Consider it if: you want to connect and compare several data and verification vendors under one decision engine.
8. Incode: best for biometric-first verification
Incode focuses on biometrics and liveness, with strong adoption in Latin America and growing global use across banking, fintech, and workforce identity. It suits businesses that prioritize face-based verification and re-authentication.
Consider it if: biometric identity and repeat authentication are central to your use case.
9. IDnow: best for European compliance and video-based verification
IDnow serves regulated European businesses with automated and video-assisted verification options and a strong focus on local regulatory requirements. It is a common choice where Europe-specific methods are required.
Consider it if: you operate mainly in Europe and need verification methods aligned to local rules.
10. Trulioo: best for global data-source verification
Trulioo specializes in verifying identities and businesses against a broad network of global data sources, in addition to document and biometric options. It fits companies onboarding customers in many countries where data-based checks are important.
Consider it if: you need wide international coverage through data-source verification.
Quick comparison
Provider | Best for | Standout strength |
|---|---|---|
Persona | Flexible workflows | Modular, configurable flows |
Sumsub | Crypto and fintech | KYC, KYB, and AML in one platform |
Jumio | Large enterprises | Mature global enterprise support |
Veriff | Fast global onboarding | Automated real-time decisions |
Onfido (Entrust) | Document and biometric checks | Part of a wider identity portfolio |
Socure | U.S. decisioning | Data-driven fraud and identity scoring |
Alloy | Orchestration | Combines multiple vendors and signals |
Incode | Biometric-first use cases | Face verification and liveness |
IDnow | European compliance | Local methods and video verification |
Trulioo | Global coverage | Data-source verification across many countries |
How to choose the right KYC solution for your business
If you are a startup or small fintech: prioritize fast integration, transparent per-check pricing, and a platform that can grow into AML and monitoring so you do not have to migrate later.
If you run a crypto or high-risk business: prioritize strong liveness and deepfake detection, injection-attack protection, and integrated AML screening. A report from Regula Forensics noted that crypto firms report some of the highest rates of AI-assisted or automated activity among users going through identity verification, which is not itself proof of fraud but does raise the bar for document authentication and biometric controls
If you are a bank or large enterprise: prioritize governance, audit trails, regional data hosting, and vendor stability.
If you serve many countries: prioritize document coverage, local database connections, and support for chip-based and wallet-based credentials.
Run a proper pilot
Before signing, test two or three finalists with your own traffic:
- Measure the genuine-user pass rate and the time to decision.
- Test with realistic fraud attempts, including replayed video and AI-generated faces, with the vendor's cooperation.
- Review how many cases fall to manual review and how easy the review tools are.
- Ask for a written breakdown of all fees, including re-verification and failed-attempt charges.
Best practices for implementing AI-powered KYC
- Layer your defenses. Combine document authentication, biometrics, liveness, and data checks instead of relying on one signal.
- Minimize the data you store. Holding fewer copies of identity documents lowers breach risk. Industry commentary this month argued that reducing the identity data available to attackers is a structural defense, not just an extra security layer.
- Tune by risk. Apply light checks to low-risk actions and step up verification for high-risk events such as large withdrawals or changes to account details.
- Plan for exceptions. Offer alternative paths for customers whose devices or documents do not support your preferred method.
- Monitor continuously. Treat KYC as ongoing, not a one-time gate.
- Document your decisions. Keep clear records of rules, thresholds, and outcomes for auditors.
Frequently asked questions
- What is the difference between KYC and AML?
KYC verifies who your customer is and assesses their risk at onboarding. AML is the broader set of controls, including transaction monitoring and suspicious activity reporting, that helps detect and prevent money laundering. KYC feeds into AML.
- How accurate is AI-powered KYC?
Accuracy varies by provider, document type, and fraud technique. Ask vendors for pass-rate and fraud-catch data from independent testing or from a pilot using your own traffic instead of relying on headline claims.
- Can AI-powered KYC detect deepfakes?
Many providers include liveness detection and deepfake or injection-attack detection, but quality differs widely. Test it directly before you buy.
- How much does KYC verification cost?
Pricing is usually per verification, often with volume tiers, minimums, or platform fees. Costs vary by checks included and by country, so request detailed quotes.
- Is chip (NFC) verification better than photo-based verification?
Reading the data stored in a document's chip can provide stronger assurance than analyzing a photo, because it validates the electronic data itself. It needs compatible devices and documents, so many businesses offer it alongside other methods.
- Do I need a different solution for business customers?
Yes, if you onboard companies. That process is called KYB (Know Your Business) and involves verifying company records and beneficial owners. Several providers above cover both.
Final thoughts
The best AI-powered KYC verification solution is the one that fits your risk profile, markets, and growth plans, and that holds up against today's AI-assisted fraud. Shortlist two or three providers, pilot them with real traffic, and watch for shifts such as chip-based checks and digital identity wallets that are already changing what "good" looks like. Revisit your choice regularly, because this market is moving fast.
Disclaimer: This article is for general informational purposes and is not legal, compliance, or financial advice. Provider capabilities, ownership, and pricing change frequently, so verify current details directly with each vendor and consult a compliance professional about your obligations.